
Key Takeaways
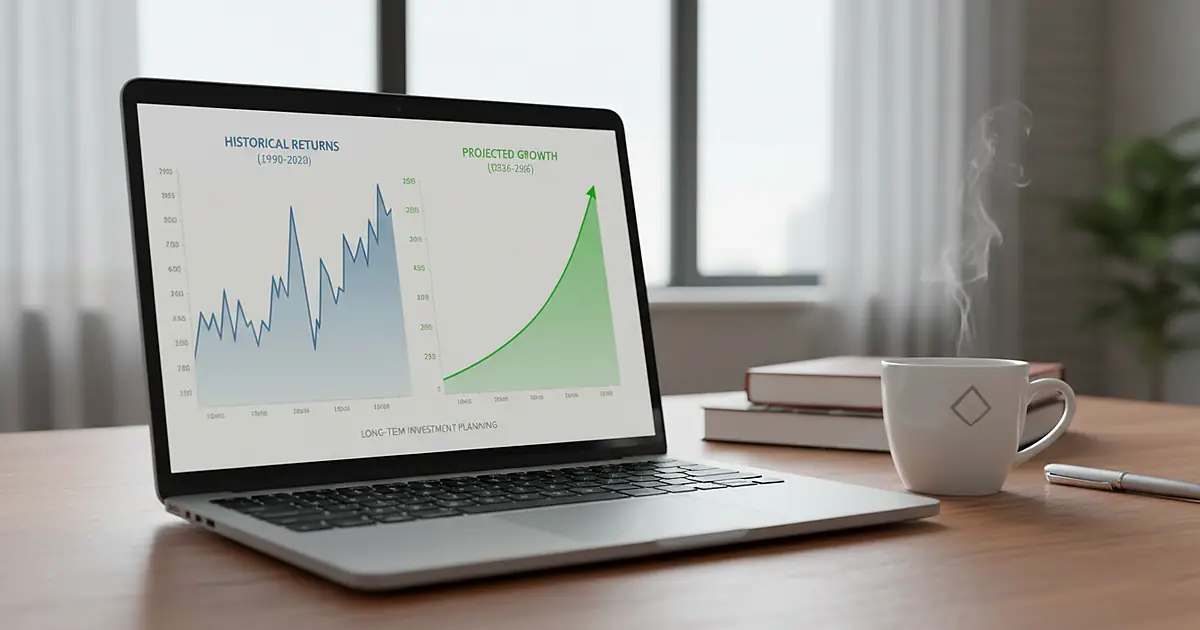
- Historical returns average ~10% for stocks, but expected returns for the next decade are projected much lower at 4-6%.
- 2026 retirement contribution limits have increased to $24,000 for 401(k)s and $7,500 for IRAs, helping offset lower expected growth.
- Pre-retirees should use conservative expected returns to avoid shortfalls, while younger investors can rely more on historical averages.
Note: This is educational content, not financial advice.
Note: This article is for educational purposes only and is not financial advice. Always consult a qualified financial advisor before making investment decisions.
You’re sitting at your kitchen table, staring at a retirement calculator. Sound familiar? You’ve got your current savings, your monthly contribution, and then there’s that one little box that changes everything: "Expected Annual Return." If you punch in 10%, you’re a multi-millionaire by 60. If you punch in 5%, you might be eating generic-brand cereal for the rest of your life. It feels like a guessing game, doesn’t it?
How you fill in that box is the difference between a retirement plan that actually works and one that’s just wishful thinking. Most of us are taught to look backward. We see the S&P 500 has averaged roughly 10% over the last century and think, "Great, I’ll just use that." But then you hear experts from places like Vanguard or BlackRock warning that the next decade might look a lot more like 4% or 5%. Honestly, it makes your plan feel shaky.
Choosing between historical averages and forward-looking expectations isn’t just a math problem. It’s a strategy for how you’ll handle the uncertainty of the next twenty or thirty years. We'll break down these two approaches so you can figure out which one belongs in your spreadsheet.
Comparing Historical vs. Expected Return Models
Last Updated: March 21, 2026
| Feature | Historical Returns | Expected Returns (2026 Outlook) |
|---|---|---|
| Data Source | Past 50–100 years of market performance. | Current valuations (CAPE ratio), yields, and growth forecasts. |
| Typical Equity Rate | ~10% Nominal / ~7% Real (Inflation-adjusted). | ~4% to 6% (Vanguard 2026 Projections). |
| Reliability | High over 30+ year horizons; low over 5–10 years. | Better for mid-term (10-year) planning and risk management. |
| Primary Risk | Recency bias and "Sequence of Returns" risk. | Analysis paralysis and potential to under-invest. |
| Best For | Younger investors (20s/30s) with long timelines. | Pre-retirees (40s/50s) and those near the finish line. |
The Case for Historical Returns: The Rearview Mirror Approach
Looking at historical returns is like checking the weather patterns of the last century to decide what to wear tomorrow. It doesn't tell you if it will rain at 2:00 PM (even if it doesn't help you with a sudden thunderstorm). But it tells you that, on average, it’s going to be hot in July. Since 1926, the S&P 500 has delivered an average annual return of about 10.2%. If you adjust that for inflation, you’re looking at roughly 7% in "real" purchasing power.
For many, this is the gold standard because it covers everything: the Great Depression, World War II, the stagflation of the 70s, the dot-com bubble, and the 2008 crash. The logic is simple: if the market survived all that and still averaged 10%, why wouldn't it continue? In our experience, the biggest strength of using historical data is that it prevents you from panicking during a bad year. If you know the market has a long-term upward trajectory, you’re less likely to sell your Fidelity index funds when the news cycle gets scary.
It encourages the kind of "buy and hold" behavior that actually builds wealth. Say you’re 25 years old, making $65,000 a year, and you decide to buy into a Roth IRA—which, for 2026, has a limit of $7,500. If you assume a



